An Asian river skyline at sunset, framed by traditional pavilion architecture.
PGMPEOPLE · GROWTH · MONEY

Where Capital Meets Opportunity.

PGM connects capital providers with businesses seeking flexible financing—creating a managed credit ecosystem designed to support borrowers while giving eligible investors access to the economics of private lending.

CAPITAL TODAY. BRIGHTER TOMORROW.

  1. ORIGINATE

    Find opportunities.

  2. UNDERWRITE

    Understand risk.

  3. STRUCTURE

    Build the financing.

  4. DEPLOY

    Put capital to work.

  5. MONITOR

    Manage performance.

  6. REPAY

    Complete the cycle.

WHY PGM EXISTS

The opportunity is
not created by PGM.It already exists.

Every day, businesses need capital.

Some need to purchase inventory.

Some need working capital while waiting for receivables.

Some need equipment.

Some are expanding.

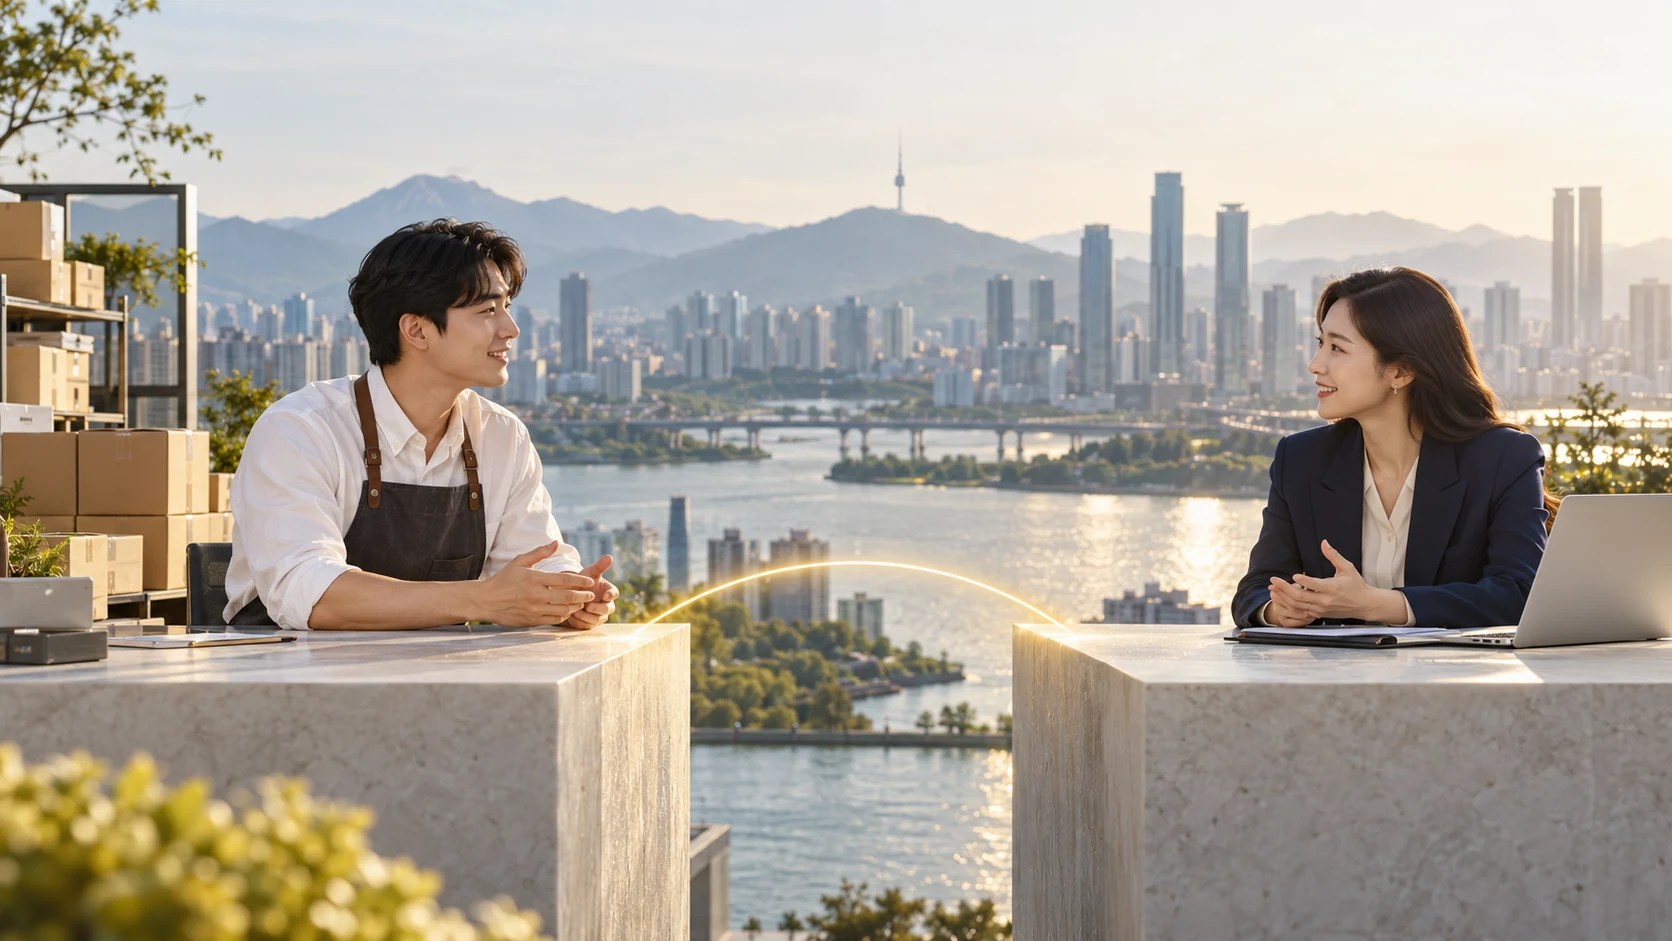
A business owner and a capital provider on opposite sides of a gap, linked by a gold arc. BORROWERSCAPITAL PROVIDERS
A glowing arched bridge at night, connecting across water to a modern illuminated city skyline.

PGM IS THE BRIDGE

The problem is not capital.
The problem is connection.

BORROWERS

“I have an opportunity.
I need capital to execute it.”
PGMPEOPLE · GROWTH · MONEY

CAPITAL PROVIDERS

“I have capital.
I want it deployed into productive opportunities.”
  1. SOURCE
  2. ASSESS
  3. STRUCTURE
  4. FUND
  5. MONITOR
  6. COLLECT

PGM doesn't create value simply by moving money.PGM creates value by improving the connection between capital and opportunity.

06 / 07

Why Each Side Participates

The best financing is not always the cheapest financing.

FOR BORROWERS

Capital designed around opportunity.

  • Certainty, when timing matters
  • Speed, when opportunity is time-sensitive
  • Flexibility, when circumstances aren't standard
  • Structures customized around the borrower's situation
FOR CAPITAL PROVIDERS

Access the economics of private lending.

Investors provide capital. PGM seeks suitable financing opportunities. Borrowers pay for the use of that capital according to agreed financing terms.

The potential return has an economic source.

08

Where Does the Money Come From?

01
INVESTOR

Provides capital

02
PGM

Deploys capital into eligible financing

03
BORROWER

Receives financing

04
BORROWER'S BUSINESS

Uses capital productively

05
BORROWER

Repays principal + applicable financing charges

06
PGM

Receives and administers repayment

07
INVESTOR

Receives distributions according to applicable program terms

Returns should follow repayment—not recruitment.
A traditional pavilion framed by cherry blossoms, overlooking a river toward a modern city skyline at sunrise.

PEOPLE → MONEY → GROWTH → PEOPLE

THE PGM FLYWHEEL

  1. PEOPLE
  2. MONEY
  3. GROWTH
  4. REPAYMENT
  5. MORE PEOPLE
PGMPEOPLE · GROWTH · MONEY

Financing supports productive economic activity.

Capital can return to investors or be redeployed.

10

PGM Is Not Just a Marketplace

A marketplace says: "Here is a borrower. Here is an investor. Good luck." PGM's ambition is to manage the credit journey.

  • Origination

    Finding opportunities

  • Underwriting

    Understanding repayment capacity

  • Structuring

    Designing financing terms

  • Portfolio Construction

    Avoiding excessive concentration

  • Monitoring

    Following borrower performance

  • Servicing

    Administering payments

  • Risk Management

    Identifying problems early

  • Recovery

    Managing delinquent financing

  • Reporting

    Showing capital providers what is actually happening

11

It shouldn't be ROI.

UNDERWRITING

Anyone can lend money. The difficult part is determining:

  • Who should receive it?
  • How much?
  • For how long?
  • At what price?
  • Against what protection?
  • How likely are they to repay?

That is what turns lending from a money-transfer business into a credit business.

ONE TRANSACTION. THREE PERSPECTIVES.

Imagine a business needs $100,000 to purchase inventory.

THE BORROWER SEES:

Capital designed around opportunity.

“With financing, I can purchase inventory today instead of waiting months to accumulate the capital.”

PGM provides access to financing, subject to approval and terms.

PGM SEES:

“Is this an appropriate credit opportunity?”

PGM assesses the financing requirement, borrower, repayment capacity and relevant risks and structures the financing where appropriate.

THE CAPITAL PROVIDER SEES:

Access the economics of private lending.

“My capital is participating in an identifiable financing activity with defined economics.”

RETURN BEGINS WITH RISK

We don't believe risk disappears because an opportunity is private.

Private credit carries real risks. Borrowers can experience financial difficulty. Payments can be delayed. Defaults can occur. Collateral, where present, can lose value. Capital may be illiquid. Actual returns can differ from targets.

  • understand it
  • price it
  • structure around it
  • manage it

13

The PGM Credit Philosophy

  1. 01

    Purpose Before Capital

    Understand why the borrower needs financing before providing it.

  2. 02

    Repayment Before Return

    Understand how capital is expected to come back before focusing on what it may earn.

  3. 03

    Structure Before Scale

    Build appropriate financing structures before pursuing volume.

  4. 04

    Diversification Before Concentration

    Avoid allowing one borrower, sector or financing type to determine the health of the entire portfolio.

  5. 05

    Transparency Before Promotion

    Show investors how the credit engine works before promoting potential returns.

14

From Borrower to Portfolio

A single loan is an opportunity.A well-managed collection of loans becomes a portfolio.

"My capital participates in a managed credit portfolio."

  • Borrowers
  • Industries
  • Loan Sizes
  • Financing Purposes
  • Durations
  • Geographies
  • Repayment Profiles

15

What Investors Should Eventually See

Illustrative only — PGM will display metrics it can actually substantiate.

$10.6M Capital Deployed Illustrative Preview — PGM will display metrics it can actually substantiate.
10.6MActive Financing $15,000Average Loan Size 14 daysAverage Duration 26.8%Portfolio Yield 99.6%Repayment Rate 0.4%Delinquency Rate 0%Default Rate 100%Capital Utilization
Industry Exposure
  • Trade & Retail28%
  • Manufacturing22%
  • Logistics18%
  • Services17%
  • Other15%
Geographic Exposure
Maturity Schedule

18

Behind Every Loan Is a Reason.

  • A retailer preparing for peak season.
  • A manufacturer purchasing equipment.
  • A merchant financing inventory.
  • A company bridging receivables.
  • An entrepreneur expanding an established operation.

They don't necessarily need money for money's sake.They need what money makes possible.

19

And Behind Every Investment Is an Objective

  • Income
  • Diversification
  • Capital Preservation
  • Long-Term Compounding
  • Portfolio Construction

The borrower wants useful capital.

The investor wants productive capital.

PGM seeks to make the same capital accomplish both.

PEOPLE · GROWTH · MONEY

Money alone doesn't create progress.

It needs somewhere productive to go.